Introduction
Being a nurse can provide a good income, but earning more money does not automatically mean building wealth.
After long shifts, overtime, stressful patient assignments, and the emotional demands of healthcare, it can be surprisingly difficult to feel financially secure. A nurse may earn a strong salary and still feel like the money disappears between paychecks.
Bills, student loans, credit card balances, housing costs, insurance, childcare, everyday expenses, and unexpected emergencies can quickly compete for the same paycheck.
That is why money tips for nurses need to go beyond simply telling you to “save more.”
Nurses need financial strategies that actually fit the reality of working in healthcare.
You may work three 12-hour shifts one week and pick up overtime the next. You may work nights, weekends, holidays, or multiple jobs. You may be paying for professional licenses, continuing education, scrubs, shoes, transportation, and other expenses connected to your career.
At the same time, you may be trying to build an emergency fund, pay off debt, improve your credit, invest for retirement, support your family, and create a better financial future.
It can feel like a lot.
The good news is that you do not have to fix everything at once.
Building financial stability is a process. The goal is to understand where your money is going, make intentional decisions with your income, reduce unnecessary financial pressure, and gradually build assets that can work for you.
This guide is designed to help you do exactly that.
Whether you are a nursing student, new nurse, experienced RN, travel nurse, nurse practitioner, or healthcare professional looking for greater financial freedom, these strategies can help you create a stronger financial foundation.
We will look at practical ways to manage your paycheck, control spending, build an emergency fund, handle debt, improve credit, increase income, begin investing, and build long-term wealth.
We will also discuss something traditional financial advice often ignores: how your emotions and nursing career can affect your financial behavior.
Burnout, financial stress, lifestyle inflation, emotional spending, and the pressure to maintain a certain lifestyle can all influence financial decisions.
You do not need to feel ashamed if your finances are not where you want them to be.
You need a strategy.
The goal of NurseMoneyLab is not simply to help nurses make more money. It is to help nurses understand how to keep more of what they earn, use their money intentionally, and build a future that is not dependent on working endless hours.
Your nursing income is a powerful starting point.
Now it is time to make that income work harder for you.
1. Know Exactly Where Your Nursing Income Is Going
Before you try to save more, invest more, or pay off debt, you need to understand your current financial picture.
This is especially important for nurses because income can vary significantly.
Your paycheck may include:
- Base hourly pay
- Night-shift differentials
- Weekend differentials
- Overtime
- Holiday pay
- Bonuses
- Travel stipends
- Per-diem income
- PRN shifts
- Side-hustle income
A nurse who earns $40 an hour may have a completely different financial situation from another nurse earning $40 an hour because their housing costs, debt, family responsibilities, and spending habits are different.
Start by looking at your actual take-home pay, not just your advertised salary.
Then calculate your essential monthly expenses.
These may include:
- Housing
- Utilities
- Transportation
- Groceries
- Insurance
- Childcare
- Minimum debt payments
- Phone and internet
- Medical expenses
- Professional expenses
Once you know what it costs to maintain your household, you can determine how much of your income is available for financial goals.
The goal isn’t to create a perfect budget.
The goal is to stop making financial decisions without knowing the numbers.
2. Create a Budget That Works With Your Nursing Schedule
Traditional budgeting advice often assumes that people have predictable schedules and predictable expenses.
Nursing doesn’t always work that way.
A nurse may work three shifts one week, pick up overtime the next, and then have a smaller paycheck after taking time off.
Instead of creating a budget that depends on overtime, build your basic lifestyle around your reliable income.
Treat overtime and bonuses as additional income rather than money you need to survive.
For example, you could divide extra income between several priorities:
Extra income → debt + savings + investing + enjoyment
This allows you to enjoy some of the money you worked hard to earn without allowing lifestyle expenses to permanently increase every time your paycheck does.
A flexible nursing budget should also account for irregular expenses.
Instead of being surprised by annual expenses, create sinking funds for things such as:
- Car repairs
- Insurance premiums
- Holidays
- Professional licenses
- Continuing education
- Travel
- Home maintenance
- Children’s expenses
Planning for these expenses can make your financial life much less chaotic.
3. Build an Emergency Fund Before Life Forces You To
One unexpected expense can completely disrupt a household that has no cash reserves.
A broken vehicle, medical bill, job interruption, emergency travel, or major home repair can quickly become a credit-card balance when there is no emergency fund.
For nurses, having accessible savings is particularly valuable because healthcare jobs can change quickly.
Start with a small goal.
Your first milestone might be $1,000.
Once that feels manageable, work toward one month of essential expenses. Eventually, you may want several months of essential expenses saved, depending on your household and employment situation.
Keep emergency savings somewhere separate from your everyday spending account.
The purpose of an emergency fund isn’t to make you rich.
It’s to prevent an emergency from becoming debt.
4. Stop Letting Lifestyle Inflation Eat Your Raises
Getting a raise feels good.
So does receiving a bonus, picking up overtime, or moving into a higher-paying nursing position.
The problem occurs when every increase in income immediately becomes an increase in spending.
This is known as lifestyle inflation.
You earn more, so you upgrade the apartment.
Then you upgrade the car.
Then you increase subscriptions.
Then you eat out more frequently.
Eventually, your income has increased significantly—but your financial flexibility hasn’t.
Instead of allowing every raise to disappear into lifestyle upgrades, create a rule for increases in income.
For example, you might decide that a portion of every raise goes toward financial goals before increasing discretionary spending.
You can still enjoy earning more.
The difference is that you’re making the increase work for you rather than allowing your expenses to automatically absorb it.
5. Understand Emotional Spending After Difficult Shifts
Nursing can be emotionally exhausting.
After a difficult shift, spending money can sometimes feel like a reward for surviving the day.
You may order takeout because you’re exhausted.
You may buy something online because you deserve a treat.
You may book a trip because you desperately need a break.
Occasional spending isn’t the problem.
The problem occurs when shopping, eating out, or spending becomes your primary method of emotional recovery.
If you notice yourself spending more after stressful shifts, don’t immediately label yourself as irresponsible.
Instead, identify the trigger.
Ask:
What happened before I wanted to spend money?
Was it exhaustion?
Stress?
Loneliness?
Frustration?
Feeling unappreciated?
Wanting to reward yourself?
Once you understand the trigger, you can create alternatives that provide relief without automatically affecting your bank account.
You can read more about this in our guide on emotional spending after nursing shifts.
6. Make a Plan for High-Interest Debt
Not all debt has the same financial impact.
High-interest credit card debt can make it extremely difficult to build wealth because interest continues working against you.
Start by listing your debts.
Write down:
- Balance
- Interest rate
- Minimum payment
- Due date
Then choose a repayment strategy.
Two common approaches are the debt avalanche and debt snowball.
The debt avalanche focuses on paying the highest-interest debt first.
The debt snowball focuses on paying the smallest balance first.
The mathematically efficient strategy isn’t always the strategy someone can stick with.
Choose an approach that helps you remain consistent.
And avoid adding new debt while aggressively paying off old balances whenever possible.
7. Use Your Credit as a Financial Tool
Your credit history can affect more than whether you qualify for a credit card.
Credit can influence borrowing costs, housing opportunities, insurance pricing in some situations, and other financial decisions.
If your credit needs improvement, start with the fundamentals.
Focus on:
- Paying bills on time
- Keeping credit utilization under control
- Reviewing your credit reports
- Avoiding unnecessary new accounts
- Paying down revolving debt
- Disputing inaccurate information
You don’t need a perfect credit score overnight.
Improving credit is a process.
For a step-by-step starting point, see our guide on how to build credit from scratch.
8. Don’t Depend on Overtime as Your Only Wealth Strategy
Overtime can be an excellent way to increase income.
But there is an important distinction between earning more and building wealth.
If your financial plan requires you to continuously work extra shifts just to pay your bills, your income may be high but your financial system may still be fragile.
Think of overtime as a tool.
Use additional income strategically.
For example, extra shifts could help you:
- Build your emergency fund
- Pay down high-interest debt
- Fund retirement accounts
- Invest
- Save for a major purchase
- Build a business
- Create additional income streams
The long-term goal is to gradually create a financial situation where your future does not depend on working every available shift.
9. Find Ways to Increase Your Nursing Income
Sometimes the fastest way to improve your financial situation isn’t cutting another $20 from your monthly budget.
It may be increasing your income.
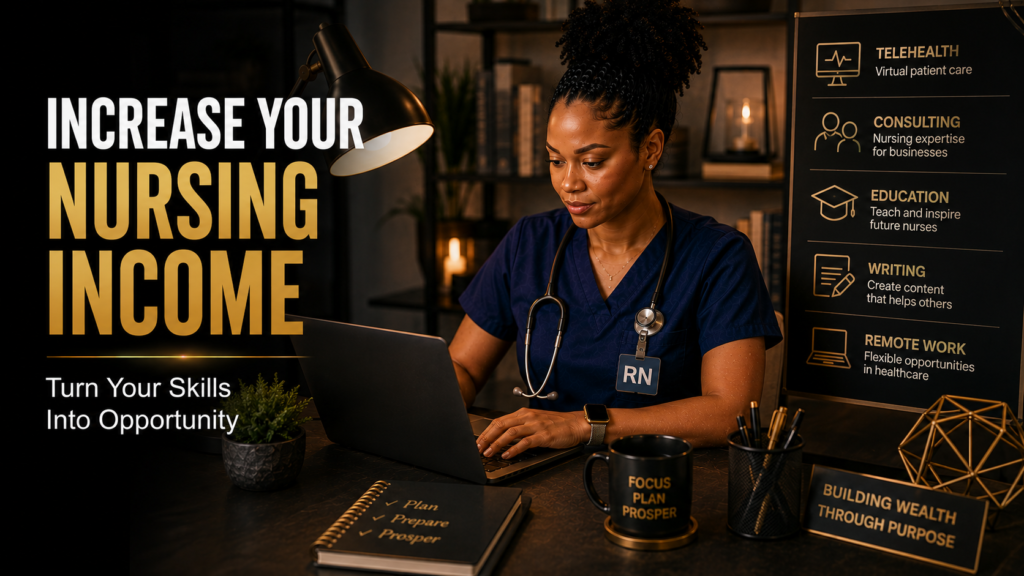
Nurses have numerous opportunities to earn beyond their primary bedside position.
Depending on your credentials and experience, possibilities may include:
- PRN nursing
- Travel nursing
- Telehealth
- Case management
- Utilization review
- Chart review
- Nurse education
- CPR instruction
- Legal nurse consulting
- Healthcare writing
- Clinical consulting
- Remote nursing positions
You can also explore online income opportunities that use your nursing knowledge without requiring you to work another traditional bedside shift.
The goal isn’t to fill every free hour with work.
The goal is to identify income opportunities that can improve your financial position without creating another source of burnout.
10. Start Investing Even If You Don’t Feel Rich
Investing can seem intimidating when you’re just starting.
You may think you need thousands of dollars before opening an investment account.
You don’t.
The bigger issue is understanding what you’re investing in and choosing investments that match your goals and risk tolerance.
Beginners often explore options such as:
- Employer retirement plans
- IRAs
- Broad-market index funds
- ETFs
- Target-date retirement funds
If your employer offers a retirement plan with matching contributions, understand how the match works.
An employer match can be an important part of your overall compensation.
Investing also requires patience.
You don’t need to constantly watch the market or chase whichever stock is trending on social media.
For a deeper introduction, read our Beginner Investing Guide for Nurses.
11. Make Retirement Part of Your Financial Plan
Retirement may feel far away when you’re focused on today’s bills.
But time is one of the biggest advantages you have as an investor.
The earlier you begin contributing, the more time your money potentially has to grow.
Nurses should review the retirement options available through their employers and understand how contributions work.
Depending on your circumstances, you may also explore individual retirement accounts and other retirement strategies.
The important thing is to avoid treating retirement as something you’ll “deal with later.”
Even small contributions can help establish the habit.
As your income increases, you can gradually increase your contributions.
12. Protect the Income That Supports Your Family
Financial planning isn’t only about investing.
It’s also about protecting what you’ve already built.
As a nurse, your ability to earn an income may be one of your most valuable financial assets.
That makes insurance and risk management important parts of a financial plan.
Depending on your circumstances, you may want to review:
- Health insurance
- Disability insurance
- Life insurance
- Auto insurance
- Home or renters insurance
- Professional liability coverage
The right coverage depends on your individual situation.
The important point is to understand what protection you already have through your employer and what gaps may exist.
Making more money doesn’t help much if one unexpected event can erase years of progress.
13. Build Multiple Sources of Income
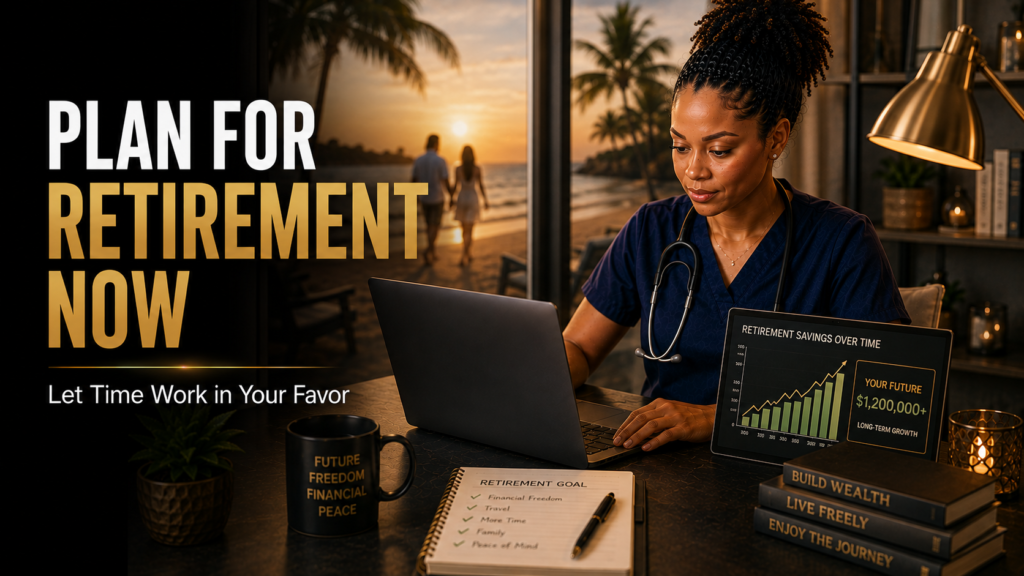
A strong financial future doesn’t necessarily require five businesses.
It does require thinking beyond a single paycheck.
Your income could eventually come from several sources, such as:
Primary nursing income
↓
Retirement investments
↓
Side income
↓
Digital products
↓
Business income
↓
Investment income
You don’t need to build all of these simultaneously.
Start with one.
For example, a nurse might begin by creating a digital nursing resource. Another might start freelance healthcare writing. Someone else might invest consistently through an employer retirement plan.
The objective is to gradually reduce dependence on one source of income.
14. Turn Your Nursing Knowledge Into an Asset
Your nursing knowledge has value outside the hospital.
You have spent years learning clinical concepts, communicating with patients, solving problems, navigating healthcare systems, and developing specialized knowledge.
That expertise can potentially become products or services.
Examples include:
- Nursing study guides
- Educational workbooks
- Online courses
- Templates
- Nursing planners
- Tutoring
- Skills education
- Healthcare content
- Consulting
- Membership communities
Digital products can be especially interesting because they can be created once and sold repeatedly.
This doesn’t mean every nurse needs to become an entrepreneur.
It simply means your professional knowledge may have value beyond your hourly wage.
15. Avoid Trying to Fix Your Entire Financial Life at Once
One of the biggest financial mistakes is attempting to change everything simultaneously.
You decide you’re going to:
- Pay off $20,000 of debt
- Save $10,000
- Start investing
- Fix your credit
- Start a business
- Stop eating out
- Work overtime
- Create a side hustle
Two weeks later, you’re exhausted and have abandoned the entire plan.
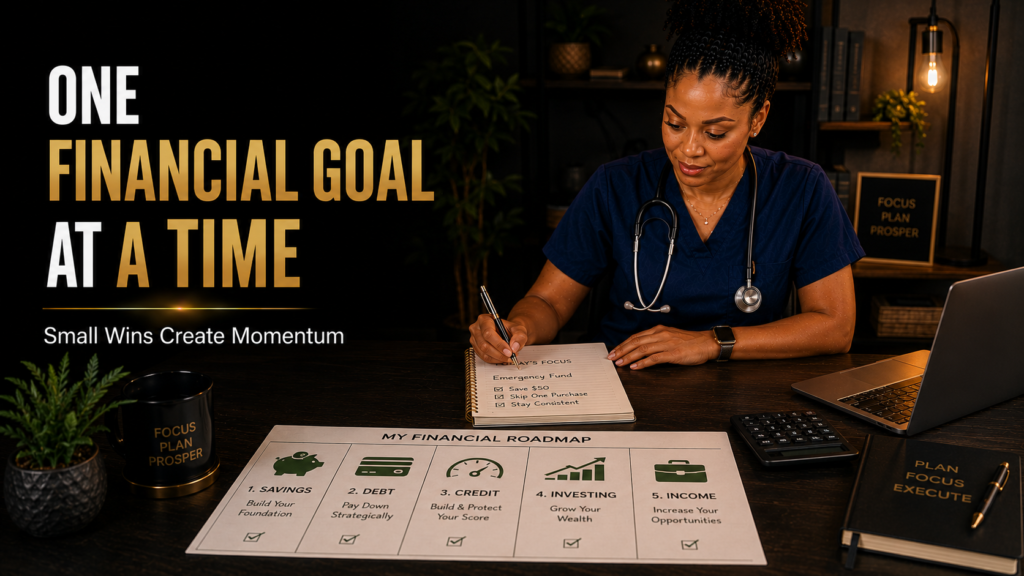
Instead, choose one primary financial goal.
For example:
Month 1: Build a starter emergency fund.
Month 2: Create a debt repayment plan.
Month 3: Automate retirement contributions.
Month 4: Improve credit.
Month 5: Explore an additional income stream.
Small wins create momentum.
Financial progress doesn’t have to happen all at once to be meaningful.
16. Create a Financial System That Runs Automatically
Motivation is unreliable.
Automation is easier.
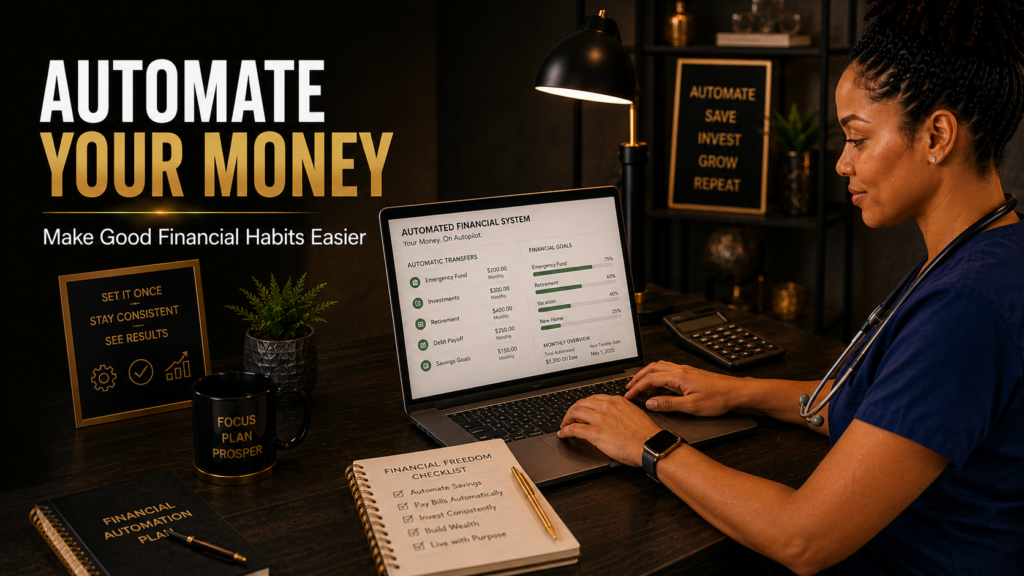
Whenever possible, automate important financial behaviors.
You can potentially automate:
- Emergency fund contributions
- Retirement contributions
- Investment contributions
- Bill payments
- Debt payments
- Savings transfers
For example, instead of waiting until the end of the month to see what money is left, move money toward your goals shortly after receiving your paycheck.
This changes saving from something you have to remember to do into part of your normal financial system.
Your goal should be to make good financial decisions easier.
17. Give Yourself Permission to Enjoy Your Money
Financial responsibility does not mean never spending money on yourself.
You worked hard for your income.
You should be able to enjoy some of it.
The difference is between intentional spending and spending that leaves you stressed afterward.
Create room in your budget for things you genuinely enjoy.
That might include:
- Travel
- Restaurants
- Beauty
- Entertainment
- Clothing
- Family activities
- Hobbies
When enjoyment is intentionally included in your financial plan, you are less likely to feel like every purchase is a failure.
The goal isn’t deprivation.
It’s control.
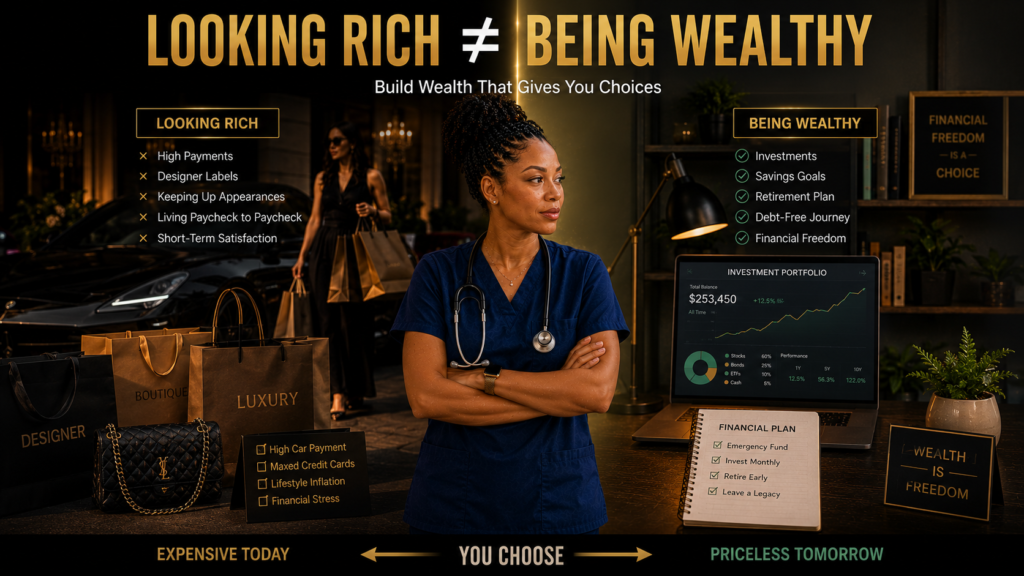
18. Build Wealth Instead of Just Looking Wealthy
There is a major difference between looking financially successful and actually becoming financially secure.
A new luxury vehicle may look impressive.
So can an expensive vacation, designer items, or a large house.
But wealth is not determined by appearances.
True financial progress may look much less exciting.
It can look like:
- A growing emergency fund
- Lower credit card balances
- Increasing retirement contributions
- Investments accumulating over time
- A paid-off vehicle
- Improved credit
- Multiple income sources
- Reduced financial anxiety
You don’t have to prove your financial success to anyone.
Build the kind of financial life that gives you more choices.
19. Create Your Personal Nurse Wealth Plan
There is no single financial plan that works for every nurse.
Your strategy should reflect your income, debt, family responsibilities, career stage, goals, and risk tolerance.
A simple starting framework is:
Step 1: Know your numbers
Understand your income, expenses, debt, savings, and credit.
Step 2: Stabilize
Build emergency savings and create a sustainable spending plan.
Step 3: Eliminate expensive debt
Prioritize high-interest debt while avoiding unnecessary new balances.
Step 4: Protect yourself
Review insurance and other forms of financial protection.
Step 5: Invest consistently
Take advantage of appropriate retirement and investment opportunities.
Step 6: Increase income
Look for opportunities that use your nursing skills strategically.
Step 7: Build assets
Work toward investments, businesses, and other assets that can grow over time.
Step 8: Review your progress
Your financial plan should evolve as your career, income, and family situation change.
Conclusion: Your Nursing Income Can Become the Foundation for Wealth
Your nursing paycheck is more than money that arrives every two weeks.
It is a resource.
How you use that resource can determine whether you remain dependent on every paycheck or gradually build financial flexibility.
You don’t need to become wealthy overnight.
You don’t need to work endless overtime.
You don’t need to understand every investment strategy before getting started.
You need a plan that fits your life.
Start by understanding your numbers.
Build a financial cushion.
Control high-interest debt.
Protect your income.
Use your nursing skills to increase your earning potential.
Invest consistently.
And most importantly, give yourself time.
There may be seasons when you’re focused on survival and other seasons when you’re able to aggressively build wealth. That’s normal.
What matters is continuing to move forward.
The goal of Money Tips for Nurses isn’t to tell you that every nurse should have the same financial strategy.
It’s to show you that your nursing career can be the beginning of something much bigger.
Your income can pay your bills.
Your habits can create stability.
Your investments can build assets.
Your knowledge can create additional income.
And over time, those pieces can work together to create something many nurses desperately want:
financial freedom and more control over their lives.
You worked hard to become a nurse.
Now it’s time to make your money work harder for you.
Frequently Asked Questions: Money Tips for Nurses
1. How much money should a nurse save for emergencies?
A good starting goal is to build enough savings to cover unexpected expenses, then gradually work toward several months of essential living expenses. The right amount depends on your income, household responsibilities, debt, and job stability.
2. What should nurses prioritize first: saving or paying off debt?
For many nurses, it makes sense to do both. Start with a small emergency fund so an unexpected expense does not immediately go onto a credit card, while putting extra money toward high-interest debt.
3. How can nurses stop emotional spending after difficult shifts?
Start by identifying your triggers. If shopping, takeout, or online purchases usually happen after stressful shifts, create a replacement routine such as taking a shower, resting, walking, meal prepping, or setting aside a small planned amount for guilt-free spending.
4. How can a nurse make more money without working endless overtime?
Consider income sources that use your existing skills without adding another bedside shift. Options can include remote nursing, teaching, CPR instruction, freelance healthcare writing, digital products, consulting, or other flexible opportunities.
5. Should nurses invest even if they still have debt?
It depends on the type and interest rate of the debt and your overall financial situation. High-interest debt generally deserves significant attention, but completely delaying long-term investing may also mean missing opportunities to build wealth over time.
6. How much should nurses invest each month?
There is no single amount that works for everyone. A better starting point is an amount you can consistently invest without neglecting essential bills, emergency savings, or high-interest debt. Even a small recurring contribution can help establish the habit.
7. What is the best way for a nurse to start building wealth?
Start with the basics: understand your cash flow, build emergency savings, manage high-interest debt, protect your income, take advantage of appropriate retirement accounts, and invest consistently for the long term.
8. Can nurses build wealth without earning a six-figure salary?
Absolutely. A high income can make wealth building easier, but income alone does not create wealth. Consistent saving, controlled spending, investing, debt management, and increasing your income over time can all contribute to financial progress.
9. What is the biggest financial mistake nurses should avoid?
One common mistake is assuming that a higher nursing income automatically means financial security. Lifestyle inflation, excessive debt, emotional spending, and relying heavily on overtime can prevent a strong income from turning into lasting wealth.
10. Where should nurses start if they feel completely overwhelmed by their finances?
Start with one number: your monthly take-home income. Then identify your essential expenses, minimum debt payments, and current savings. You do not need to solve your entire financial life in one weekend. Start by understanding where your money is going, then tackle one financial goal at a time.
Disclaimer
This article is for educational and informational purposes only and does not constitute financial, investment, tax, insurance, or legal advice. Investing involves risk, including possible loss of principal. Consider your individual financial circumstances and consult a qualified financial professional before making investment or financial decisions.